

Jan-Sep 2026 Global EV Battery Separator Loading at 16,218Mil ㎡, Up 24.8% YoY
- Chinese Separator Makers' Share at 92.2% in Q3 2026, Up 4.0%p YoY
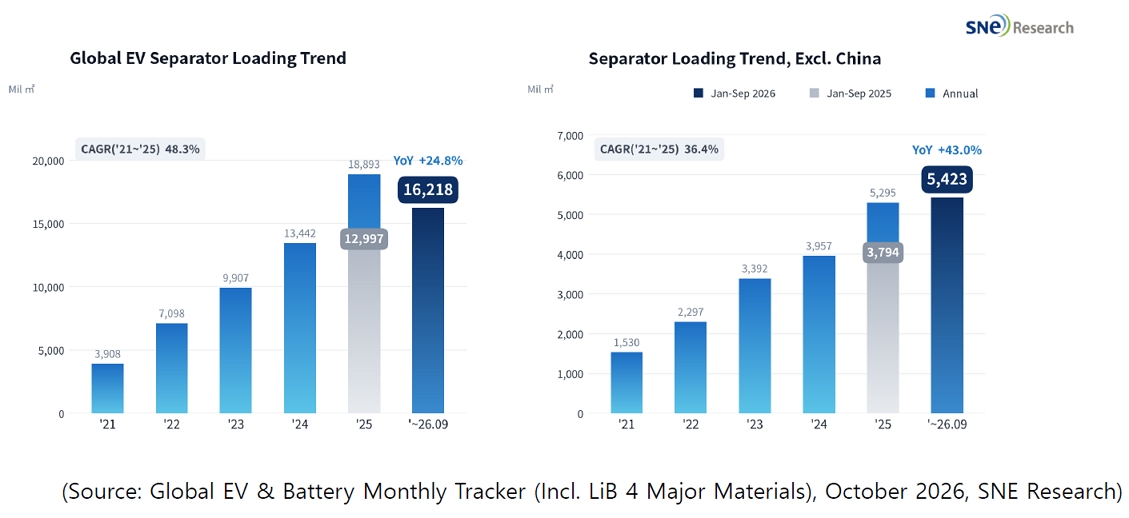
In Jan-Sep 2026, separator loading in batteries of EVs (EV, PHEV, HEV) registered worldwide was approximately 16,218Mil ㎡, up 24.8% from 12,997Mil ㎡ in the same period last year. Over the same period, the market excluding China grew 43.0% to approximately 5,423Mil ㎡, well ahead of overall growth, and its share of total loading expanded 4.2%p from 29.2% to 33.4%.
A separator is a material that keeps the cathode and anode from touching inside a battery to prevent short circuits, while its fine pores provide a pathway for lithium ions to move. Thickness, pore structure, and heat resistance determine battery safety, power, and lifespan. As cells grow larger and demand for fast charging rises, thin yet heat-resistant coated products are gaining share.
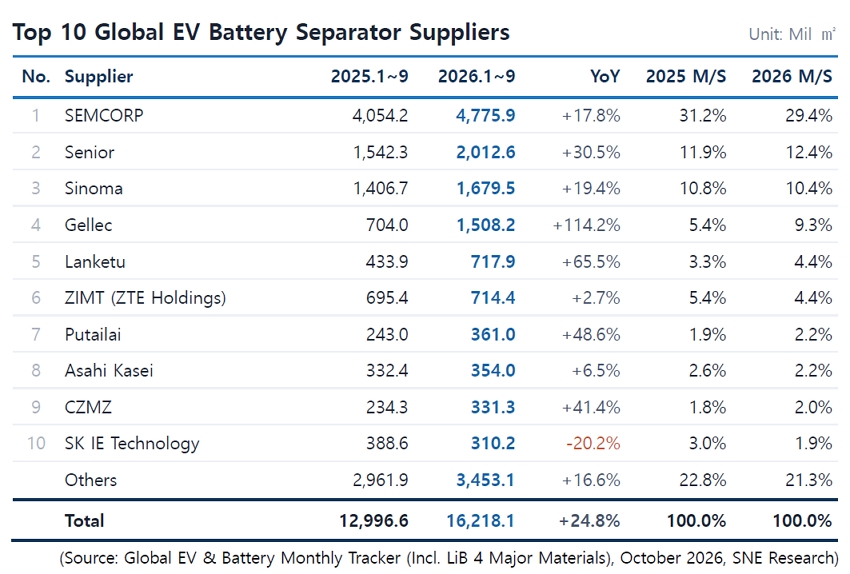
By company, SEMCORP kept first place with approximately 4,776Mil ㎡, up 17.8%, while Senior (30.5%) and Sinoma (19.4%) held second and third. Gellec solidified fourth place with approximately 1,508Mil ㎡, up 114.2%, and Lanketu rose to fifth with approximately 718Mil ㎡, up 65.5%, narrowly ahead of ZIMT (ZTE Holdings). Putailai (48.6%) and CZMZ (41.4%) also expanded quickly, with CZMZ moving up one spot to ninth. In contrast, ZIMT grew only 2.7%, Asahi Kasei rose 6.5%, and SK IE Technology fell 20.2%, dropping to tenth.
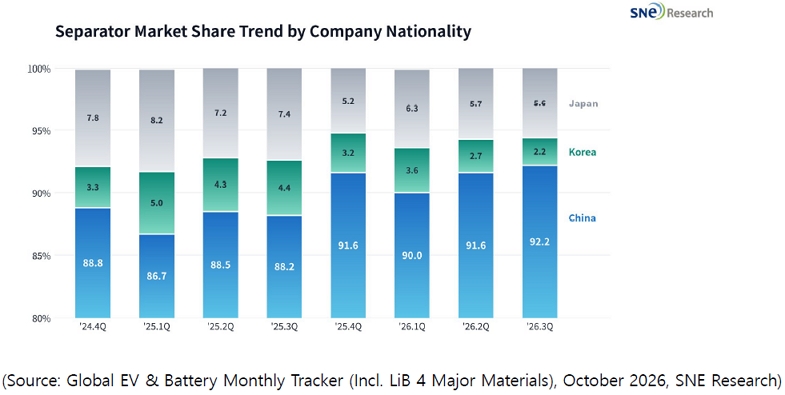
By nationality, Chinese companies' share in Q3 2026 was 92.2%, up 0.6%p from Q2 (91.6%) and 4.0%p from the same quarter last year (88.2%). Over the same period, Japanese companies' share fell from 7.4% to 5.6% and Korean companies' share from 4.4% to 2.2%. As Chinese companies with scale and cost competitiveness absorb most of the added demand, Korean and Japanese companies are restructuring their businesses around high-value products, local supply in North America and Europe, and ESS products.
In Jan-Sep 2026, the global separator market maintained solid growth on rising battery installations and rapid expansion of the market outside China. In China, expanding cell production supported separator demand, while in Europe and Asia (excl. China), higher EV sales and growing local cell production translated into higher loading. North America, by contrast, saw battery usage fall 24.3% amid weaker EV demand, keeping utilization under pressure for regional suppliers.
Industry conditions have entered a recovery phase. As Chinese wet-process separator prices turned from flat to rising in Q3, SEMCORP posted a net profit of about CNY 970 million in Q3 alone, lifting its gross margin to 36.6%, and Senior's average selling price also rose from the previous quarter. The industry expects supply to stay tight through next year on growing demand for ultra-thin separators for large ESS cells, and SEMCORP, Putailai, CZMZ, and others have launched large-scale capacity expansions, but most of the new capacity is not expected to come online until late 2027 or later. In Korea, SK Innovation plans to absorb SK IE Technology through a merger effective January 1, 2027 and expand into areas such as ESS separators. Future competitiveness is expected to hinge on EV and ESS customer diversification, ultra-thin and high heat-resistance product technology, local supply systems in North America and Europe, and the pace of cost structure improvement.