

Global EV Battery Anode Material Consumption Reaches 1,202K tons in Jan-Sep 2026, Up 21.1% Year-on-Year
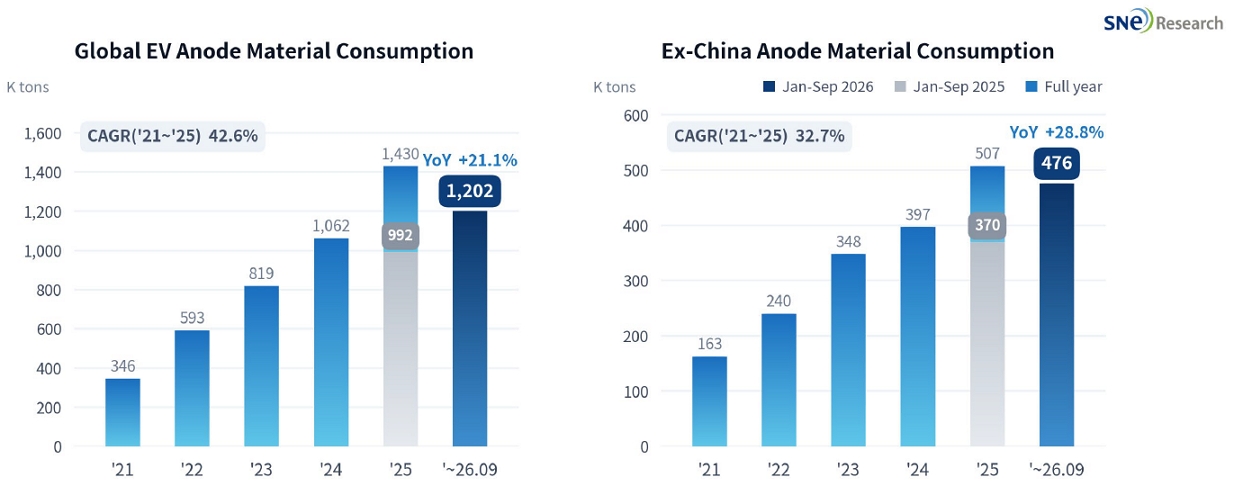
- Ex-China market reaches 476K tons, up 28.8% year-on-year
(Source: Global EV & Battery Monthly Tracker (Incl. LiB 4 Major Materials), October 2026, SNE Research)
Global anode material consumption for electric vehicles reached 1,202K tons in January-September 2026, up 21.1% from 992K tons a year earlier. Anode consumption in the ex-China market rose 28.8% from 370K tons to 476K tons, above the global growth rate (21.1%), and its share of the total rose 2.3 percentage points from 37.3% to 39.6%.
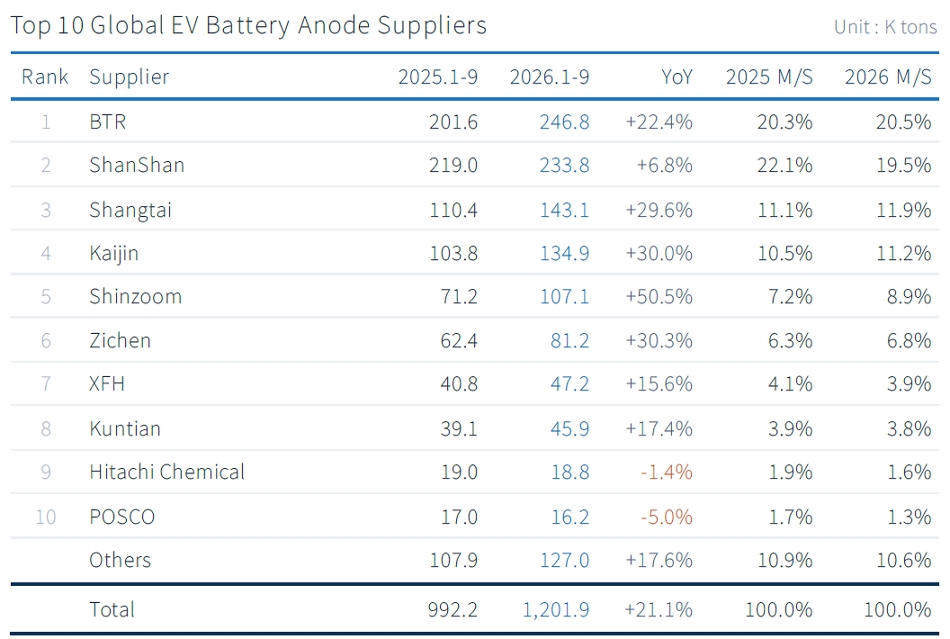
BTR ranked first with 247K tons, up 22.4% year-on-year, and ShanShan second with 234K tons, up 6.8%. The combined share of BTR and ShanShan fell from 42.4% to 40.0%, while the shares of the third- to sixth-placed suppliers each rose.
Shinzoom grew 50.5% to 107K tons, the highest growth rate among the top 10. Kaijin (135K tons) and Zichen (81K tons) grew 30.0% and 30.3% respectively, and third-placed Shangtai rose 29.6% to 143K tons. The gap between Shangtai and Kaijin was 8K tons.
XFH (47K tons) and Kuntian (46K tons) grew 15.6% and 17.4% respectively. Japan's Hitachi Chemical recorded 19K tons, down 1.4%, and POSCO 16K tons, down 5.0% year-on-year. All eight Chinese suppliers in the top 10 increased their consumption from a year earlier.
(Source: Global EV & Battery Monthly
Tracker (Incl. LiB 4 Major Materials), October 2026, SNE Research)
(Source: Global EV & Battery Monthly Tracker (Incl. LiB 4 Major Materials), October 2026, SNE Research)
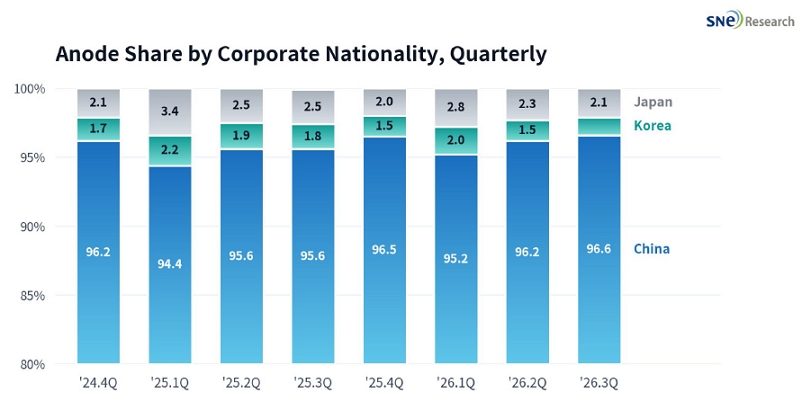
Looking at shares by nationality in the third quarter of 2026, Chinese suppliers held 96.6%, up 0.4 percentage points from the previous quarter and 1.0 percentage points from a year earlier. In the same quarter, Korean suppliers held 1.3% and Japanese suppliers 2.1%, both lower than a year earlier (1.8% and 2.5% respectively). The timing of new production facilities outside China could affect suppliers' shares going forward.
Anode consumption in the ex-China market reached 476K tons, up 28.8% year-on-year. Over the same period, EV battery usage rose 33.1% in Europe and 74.1% in Asia (ex-China), while North America fell 24.3%.
Production bases outside China continue to expand. POSCO Future M is pursuing a synthetic graphite anode plant in Vietnam (targeting mass production in 2028) and a spherical graphite plant in Saemangeum (trial operation planned for early 2027). In the United States, antidumping and countervailing duty investigations into Chinese active anode material were conducted, but no duties were imposed after the International Trade Commission (ITC) issued a negative final injury determination in March.
Going forward, the ability to produce and supply products that meet regional supply-chain requirements reliably is expected to grow in importance. China's export controls on synthetic graphite anode material and related equipment and technology, announced in October last year, remain suspended until November 10 this year. With the EU battery passport taking effect in February 2027, demand for traceability at the material stage is also likely to increase.