

PRESS RELEASE GLOBAL LiB ESS
Global ESS Shipments Reach 780GWh in 1-3Q26, Up 73% as
Non-China Demand Expands
Markets outside China account for 59.9% of global shipments; residential ESS grows 152%, the fastest among the three applications
Global lithium-ion battery (LiB) ESS shipments reached 779.9GWh in the first three quarters of 2026, up 73% from 451.5GWh a year earlier, according to global market research firm SNE Research. Third-quarter shipments alone reached 286.8GWh, up 58% year on year and 7% quarter on quarter, setting a new quarterly high. China remained the world's largest single ESS market at 313.1GWh, while shipments to North America, Europe and other regions continued to grow at a faster pace.
Two trends from the first half continued through the third quarter. By region, combined shipments to North America, Europe and other regions reached 466.8GWh, or 59.9% of the global total, up from 57.3% in the first half, while China's market share changed from 48.9% to 40.1%. By application, residential ESS shipments grew 152% to 97.5GWh, the highest growth rate among the three applications, and commercial and industrial (C&I) ESS grew 57%. As trade measures and local supply-chain requirements evolve in North America and Europe, supply-chain stability, local production capacity and regulatory compliance are becoming more important in supplier selection alongside price.
Market Overview
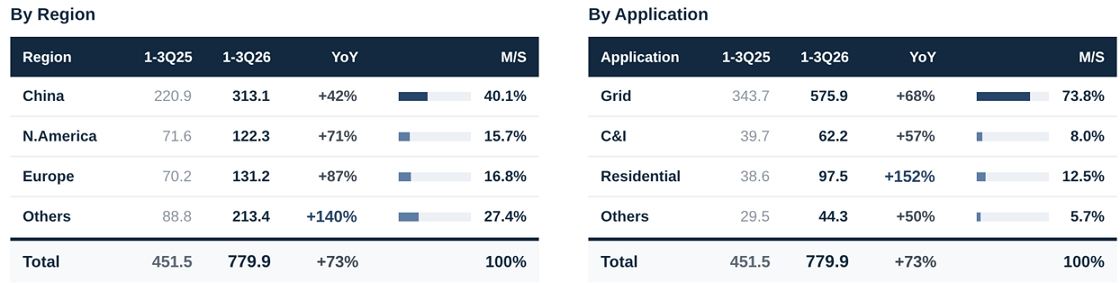
Shipments outside China continued to drive market growth in the first three quarters of 2026. China shipped 313.1GWh, up 42% year on year, maintaining its position as the largest single market, although its growth was below the overall market rate of 73%. Other Regions grew fastest at 140% to 213.4GWh, raising their share from 19.7% to 27.4%, while North America and Europe grew 71% and 87% respectively. As a result, China's market share changed from 48.9% to 40.1%, and stood at 35.8% in the third quarter alone. Within Other Regions, the Middle East (58.7GWh, +157%), Asia excluding China (48.7GWh, +153%) and Australia (54.0GWh, +113%) all recorded strong growth.
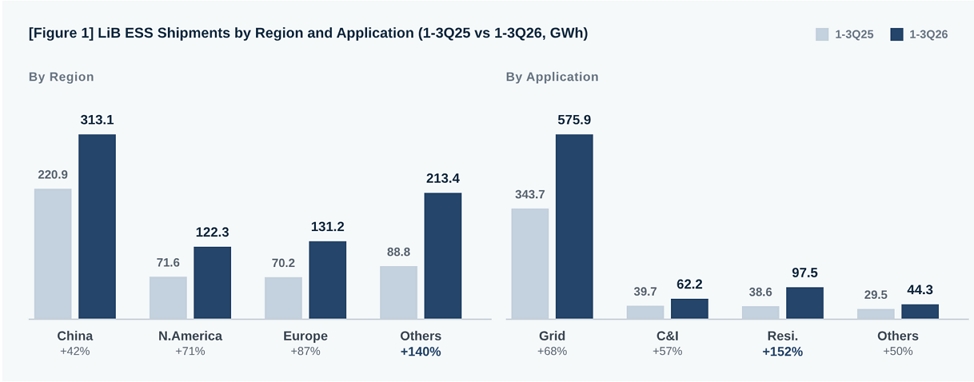
By application, grid-scale ESS remained the largest segment at 575.9GWh, or 73.8% of total shipments. Residential ESS shipments rose from 38.6GWh to 97.5GWh, a 152% increase and the highest growth rate among the three applications, raising the segment's share from 8.6% to 12.5%. Third-quarter residential shipments were 33.8GWh, down 9% from the second quarter, largely reflecting a 19% decline in shipments to Europe. C&I ESS grew 57% to 62.2GWh. Within other applications, shipments for AI data centers reached 14.4GWh, up 141% year on year.
Manufacturer Trends
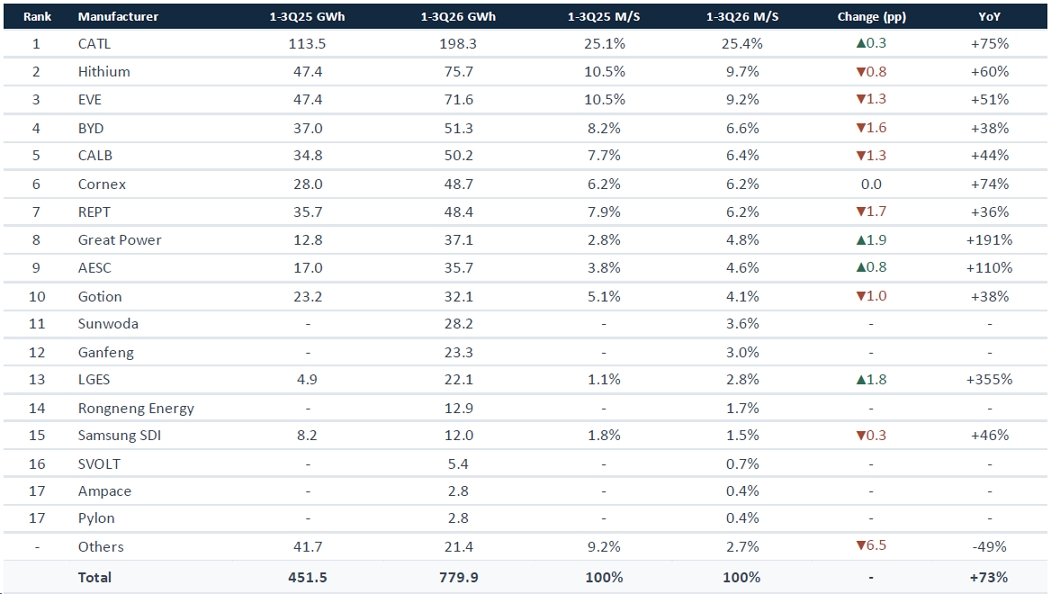
Most major manufacturers increased shipments, although growth rates and rankings shifted. CATL shipped 198.3GWh, and its market share increased from 25.1% to 25.4%. Its third-quarter shipments reached 73.3GWh, up 64% year on year. Hithium moved up from third place in the first half to second with 75.7GWh, while EVE ranked third with 71.6GWh. Great Power and AESC grew 191% and 110% respectively, well above the market average of 73%. BYD's third-quarter shipments were 15.6GWh, down 5% year on year, limiting its growth for the first three quarters to 38%.
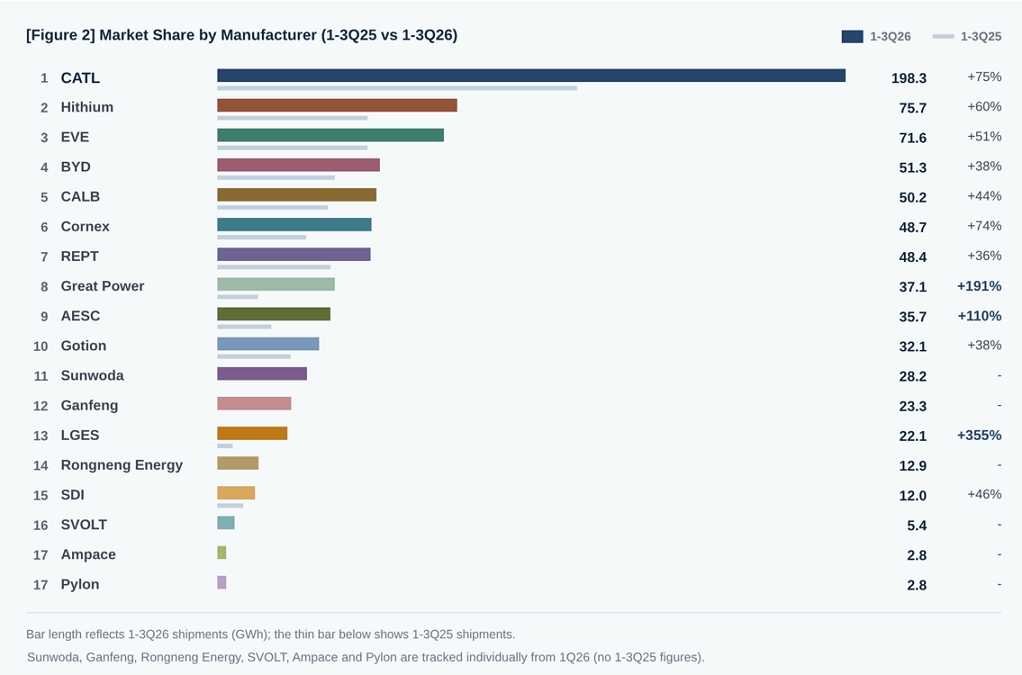
CATL kept a clear lead, while competition in the middle of the ranking intensified. Four manufacturers, from BYD in fourth place (51.3GWh) to REPT in seventh (48.4GWh), were separated by only 2.9GWh. Cornex moved up from seventh place in the first half to sixth with 48.7GWh, and ranked fifth in the third quarter alone with 18.5GWh. Great Power ranked eighth with 37.1GWh, ahead of AESC (35.7GWh). The combined share of the top three manufacturers, CATL, Hithium and EVE, fell from 46.1% to 44.3%.
From this release, Sunwoda, Ganfeng, Rongneng Energy, SVOLT, Ampace and Pylon are tracked individually. Sunwoda ranked 11th with 28.2GWh and Ganfeng 12th with 23.3GWh, followed by Rongneng Energy (14th, 12.9GWh), SVOLT (16th, 5.4GWh), and Ampace and Pylon, tied for 17th with 2.8GWh each. The six manufacturers shipped a combined 75.4GWh, or 9.7% of the global total, and residential ESS accounted for 26% of their shipments, above the market average of 12.5%.
Manufacturer Landscape by Application
3-1. Grid-scale ESS
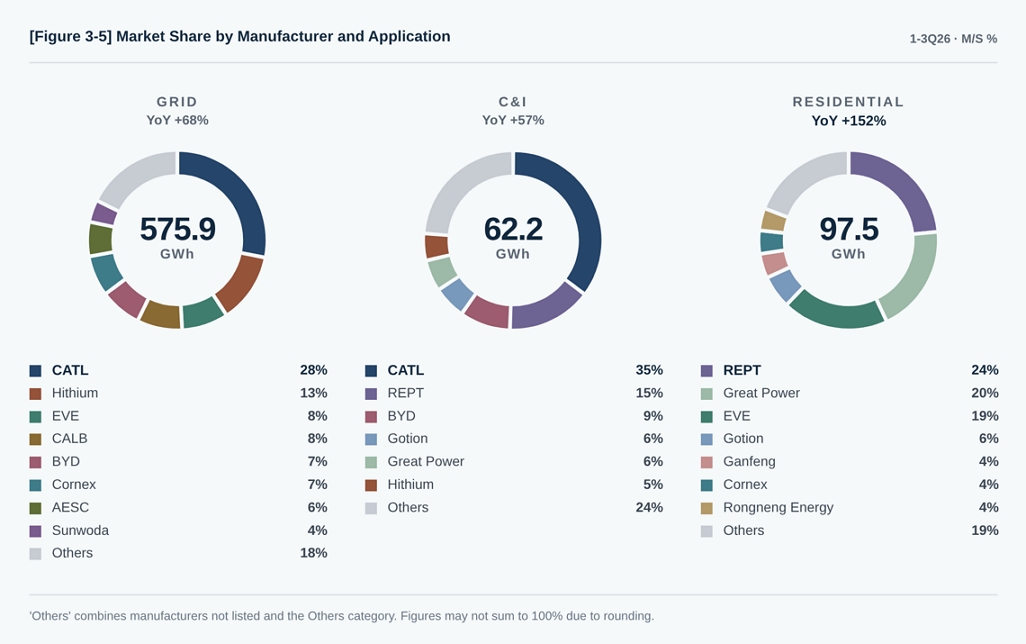
Grid-scale ESS shipments grew 68% year on year to 575.9GWh. CATL led with a 28% share, followed by Hithium at 13%, EVE at 8%, CALB at 8% and BYD at 7%, bringing the top five to approximately 65%. Cornex and AESC also remained significant suppliers at 7% and 6% respectively, with AESC's shipments up 110% and its share up 1.3 percentage points. Sunwoda, tracked individually from this release, held 4%. Grid-scale ESS accounted for 73.8% of total shipments, compared with 76.1% a year earlier, and remained the largest application.
3-2. C&I ESS
C&I ESS shipments grew 57% year on year to 62.2GWh. CATL held the leading position with a 35% share, followed by REPT at 15%, BYD at 9%, Gotion at 6% and Great Power at 6%. CATL and REPT together accounted for approximately 51%, more than half of the segment. BYD increased its shipments from 0.9GWh to 5.7GWh, raising its share by 6.8 percentage points. Ganfeng (4%) and Sunwoda (2%), tracked individually from this release, also supplied the segment, and no manufacturer outside the top two held more than 10%, indicating a comparatively broad supplier base.
3-3. Residential ESS
Residential ESS shipments grew 152% year on year to 97.5GWh, the highest rate among the three applications. REPT retained the leading position with 22.9GWh and a 24% share, followed by Great Power at 20% and EVE at 19%. REPT has ranked first in residential ESS for seven consecutive quarters since 1Q25, and led the second-ranked supplier by 3.9GWh in the first three quarters. The top three manufacturers together accounted for 62% of the segment, a higher concentration than in grid-scale (49%) or C&I ESS (60%), followed by Gotion (6%), Ganfeng (4%), Cornex (4%) and Rongneng Energy (4%). Great Power's shipments grew 293%, raising its share from 12.5% to 19.5%. The segment's share of total shipments rose from 8.6% to 12.5%.
Implications and Outlook
◆ Regional Diversification
Global ESS demand continues to spread beyond China. China remained the largest single market at 313.1GWh, with its share changing from 48.9% to 40.1%, while combined shipments to North America, Europe and other regions reached 466.8GWh, or 59.9% of the total, and 64.2% in the third quarter alone. Shipments to the Middle East and to Asia excluding China more than doubled, increasing the weight of emerging markets. As trade measures and local supply-chain requirements in North America and Europe become more stringent, local production capacity and regulatory compliance are expected to carry more weight in ESS supplier selection.
◆ Application Mix
Grid-scale ESS accounted for 73.8% of shipments, while residential and C&I ESS grew 152% and 57% respectively, lifting the residential share to 12.5%. Shipments for AI data centers reached 14.4GWh, up 141%, emerging as an additional source of demand. As data center power demand and renewable generation rise together, demand for ESS used for grid stabilization is likely to expand further.
◆ Competitive Landscape
CATL kept its lead, with its share edging up to 25.4%, while the combined share of the top three fell to 44.3% from 46.1% a year earlier. Below third place, the four manufacturers ranked fourth to seventh were separated by only 2.9GWh, and quarterly rankings shifted noticeably, with Cornex ranking fifth and BYD seventh in the third quarter. With AESC (+110%) and Great Power (+191%) growing well above the market average of 73%, and Sunwoda (28.2GWh) and Ganfeng (23.3GWh) close behind tenth-placed Gotion (32.1GWh), rankings may change again in the fourth quarter depending on the timing of large project shipments.
◆ Residential ESS
Residential ESS was the fastest-growing and most concentrated application in the first three quarters. The top three manufacturers accounted for 62% of the segment, compared with 49% in grid-scale ESS and 60% in C&I ESS. REPT held the leading position with a 24% share and has ranked first for seven consecutive quarters since 1Q25, demonstrating consistent competitiveness in this segment. Europe remained the largest destination at 33.1GWh (+140%), followed by Australia at 23.1GWh (+86%), and residential ESS is expected to remain one of the key growth segments in the coming quarters.
▷ Figures are based on SNE Research's 3Q26 ESS Tracker. Market shares and changes in percentage points are calculated from unrounded data, so results may differ by about 0.1 percentage points from figures derived directly from the rounded values shown in the tables. 'Others' represents the combined total of manufacturers not listed individually. Some 1Q26 and 2Q26 figures have been revised since the previous release. From 1Q26, Sunwoda, Ganfeng, Rongneng Energy, SVOLT, Ampace and Pylon are tracked individually; 2025 'Others' partly includes their shipments, so their 2025 figures and growth rates are not shown.